Credit infrastructure that can explain itself.
Gradexa is building the decisioning brain and the lending stack around it for India — a deterministic, explainable Credit Engine and a full CRM / LOS / LMS Suite on one data model. The same engine is designed to power our own lending product as it goes live.
A decisioning API and the Suite it powers.
Two products, one platform. Use the engine via API, adopt the Suite, or run both.
The Credit Engine
The bureau report you pulled in; risk grade, priced offer, and reasons out. Two-stage — eligibility knockouts, then 10-grade risk-based pricing — with full explainability on every response.
About the engineThe Suite
CRM, LOS, and LMS on one data model. Capture a lead, originate and decide, disburse, and service — with the engine at the center of every decision.
About the SuiteAn LMS with real depth
Servicing is where lending books go wrong. The LMS carries asset classification, interest suspense, configurable payment appropriation and per-product DPD buckets, so the ledger stays the way a regulator expects it — for single-repayment and EMI loans on the same record.
About the LMSPrinciples we won't trade away.
Explainability isn't optional
A lending decision you can't explain is a liability. Every decision returns the rules that fired and each factor's contribution — by design, not as an afterthought.
Policy belongs to credit teams
Eligibility and pricing are configuration, not code. The people who own risk can change policy without an engineering release.
One model beats four integrations
CRM, LOS, and LMS on a single data model removes the reconciliation tax that comes from stitching separate vendors together.
Honesty with a lending audience
We don't claim customers we don't have, latency we haven't measured, or integrations that aren't wired. What we say is built, is built.
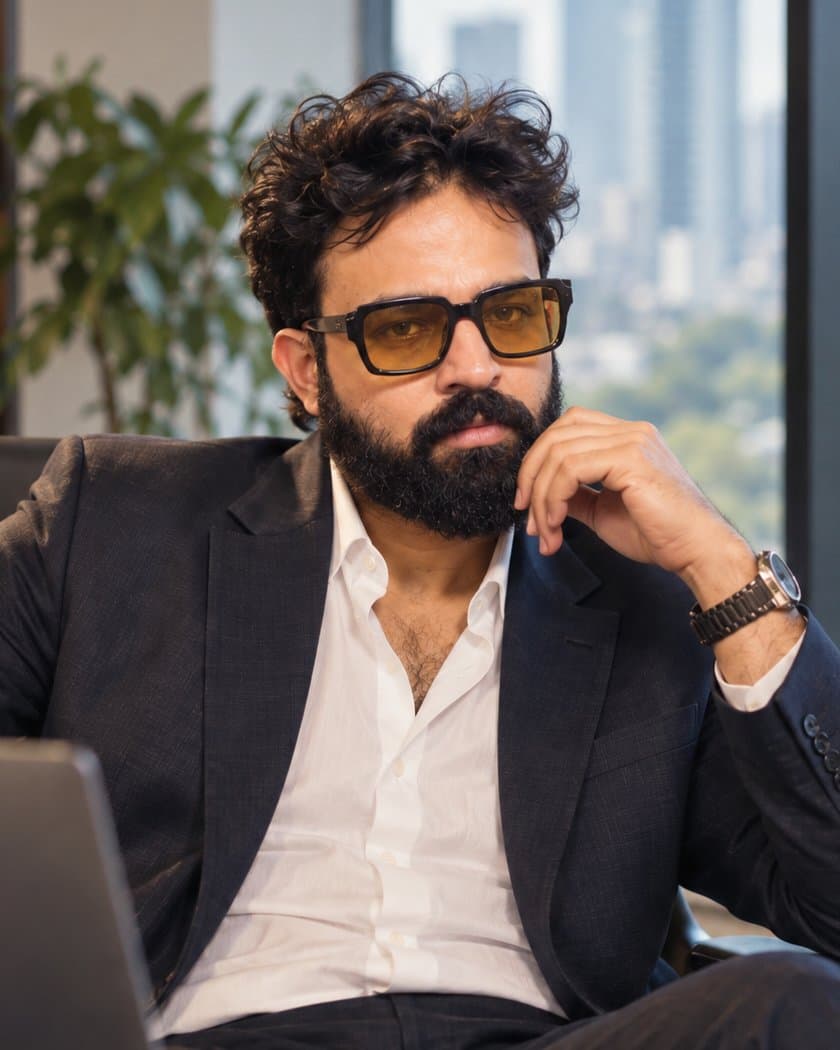
Built by an operator who has run the funnel, not just the code.
Fintech & business leader · 0→1 · 1→100 · Product · Growth · Technology
- ₹6,000Cr
- Annualised disbursal run-rate
- ₹500Cr/ month
- Disbursals, scaled from ₹50Cr in 12 months
- 97%
- Collection efficiency on the book
- 15+ yrs
- Building and scaling consumer and fintech businesses
- ₹200Cr+/ year
- Media managed
- 0→1 · 1→100
- Lending product, stack and operating model built from scratch, then scaled
Gradexa is founded by Amit Kumar Sharma, a fintech and business leader with 15+ years building, launching and scaling consumer businesses across fintech, digital lending, consumer technology and digital commerce, from 0→1 creation to 1→100 scale-up.
As Product & Growth Head at an NBFC lending app, he scaled disbursals from ₹50Cr to ₹500Cr a month within 12 months, on a book running 97% collection efficiency. Earlier he contributed to Astrotalk's growth from roughly ₹50Cr to ₹600Cr ARR, now a unicorn. His lending work spans credit and risk, KYC, underwriting, disbursals, collections, repeat lending, partnerships and distribution.
That is why Gradexa looks the way it does. Every lender he worked with lost money in the same places: decisions nobody could explain, policy changes stuck in engineering queues, and marketing data that never reconciled with loan outcomes. Gradexa puts acquisition, decisioning and servicing on one data model so those gaps close.
Experience across
- Bajaj Finserv
- Ram Fincorp
- Astrotalk
- Innovana Thinklabs
Brands scaled
- Bajaj EMI Store
- Bajaj Insurance
- Nexa
- Eicher Motors
- Pathkind Labs
- Mankind Pharma
Business Building · Fintech & Lending · Product & Technology · Growth & Distribution · Credit & Risk · Operations · Unit Economics · Partnerships · Scaling Teams
Where we are today
Gradexa is in active development. The decisioning logic, pricing grades, explainability, and the shared CRM/LOS/LMS data model are the core of the platform. The engine makes no bureau calls: clients pull the report with their own bureau membership and send it, and the engine parses and normalises it (CIBIL XML, CRIF High Mark JSON, Experian fixed-width, Equifax JSON). Direct bureau pull, soft or hard, is on the roadmap. NACH mandates are partial: core logic built, not production-ready. We have no production lenders yet — when we have lenders to name and they consent, they'll appear here, not before.
Talk to us.
If you're building or running a lending product in India and want decisioning you can defend, we'd like to hear from you.